TIAA
About This Project
TIAA manages retirement plans for members across thousands of institutions. RAS, the Retirement Accumulation System, was the digital front door into that relationship, the flow meant to turn a new participant into someone actively managing their own retirement. Instead, most people who started it never finished. The ones who got stuck called support instead, and every call started from nothing.
The Challenge
TIAA's Retirement Accumulation System was buried two clicks deep under a "Goals" tab, and the flow itself was broken. Only 8 of 100 users who started it finished. 85%+ dropped off before completing a task that was supposed to be the front door into TIAA's retirement products.
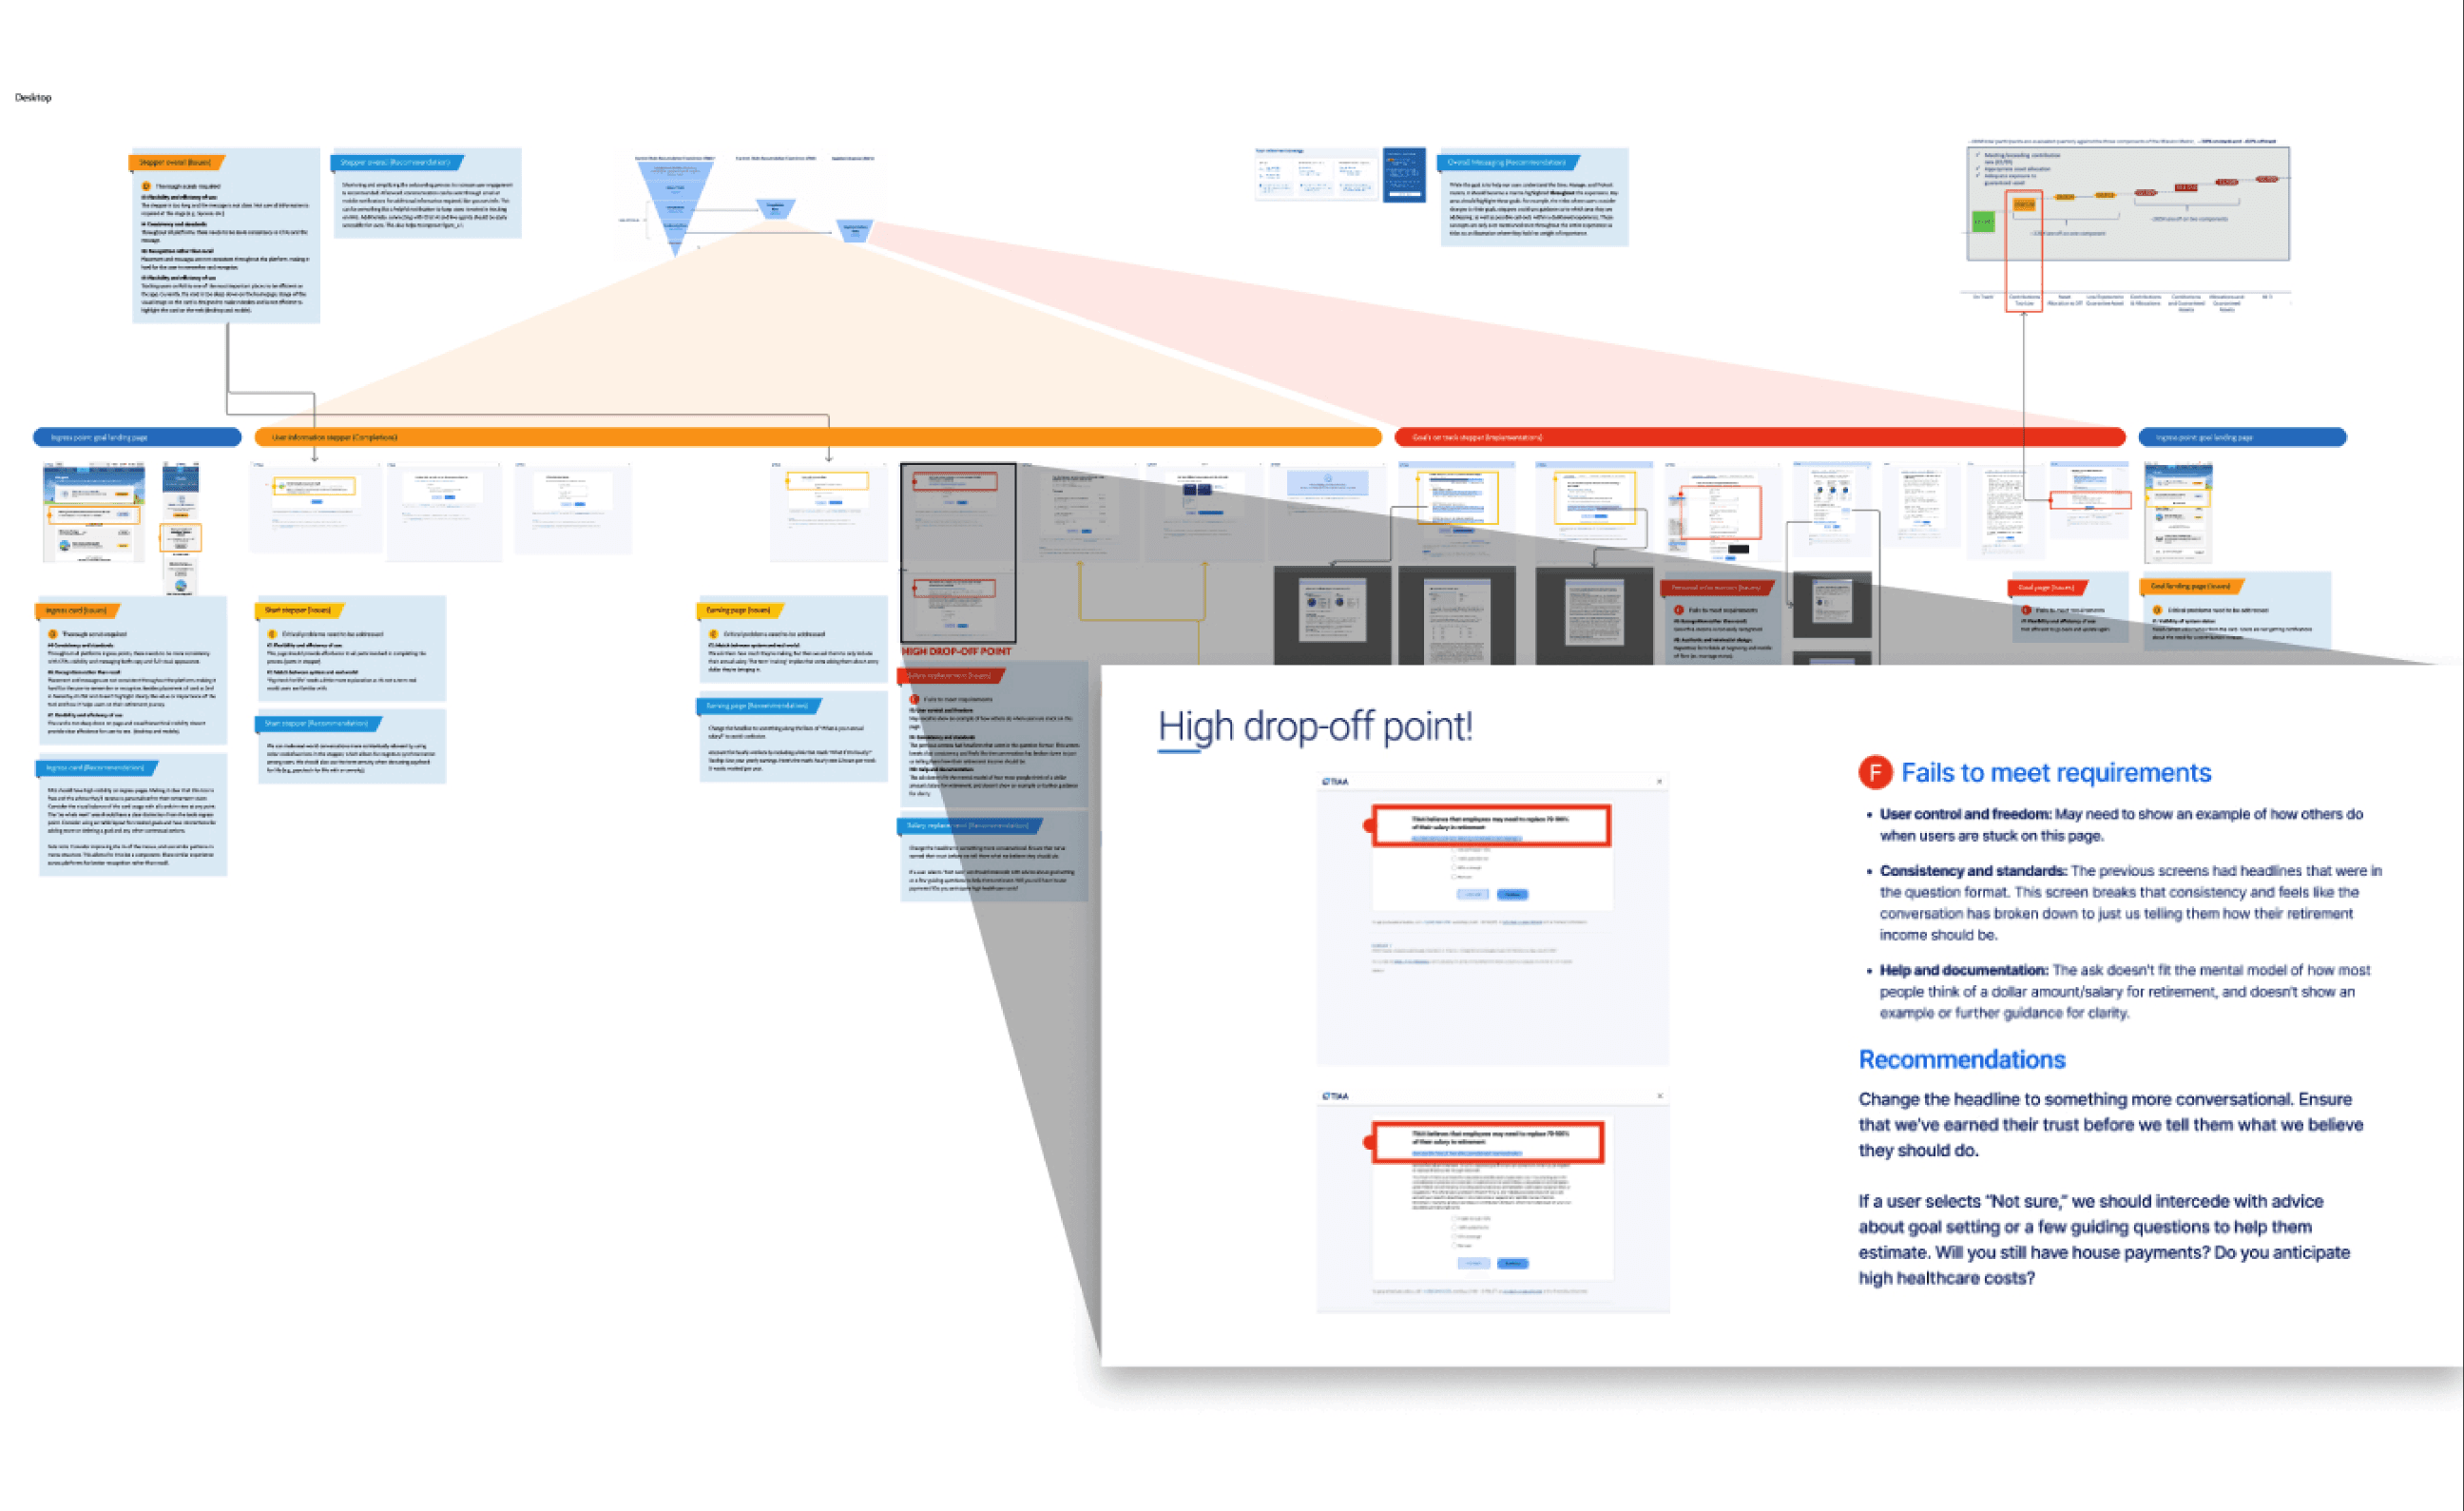
The system was supposed to convert people into TIAA's retirement products. Instead it converted them into phone calls. Users got confused, gave up, or called support, and every call started from zero, no context carried over, no sense of where the person had stopped.
The stakes made this harder than a normal onboarding flow. People were mapping out their financial future, and most didn't find out until the end whether they were on track or off track for retirement. Keeping someone engaged through that reveal, instead of losing them to confusion or panic, was as much a design problem as the drop-off numbers.
How I Approached It
I ran a heuristic evaluation on the existing flow first and built a hypothesis from it. Then I tested that hypothesis against real users, hundreds of interviews. The research confirmed most of it, but exposed a gap: financial literacy wasn't just a knowledge problem, it was a background problem. Someone raised around investing had a completely different relationship with financial products than someone with no exposure to them at all. The flow was talking to everyone the same way.
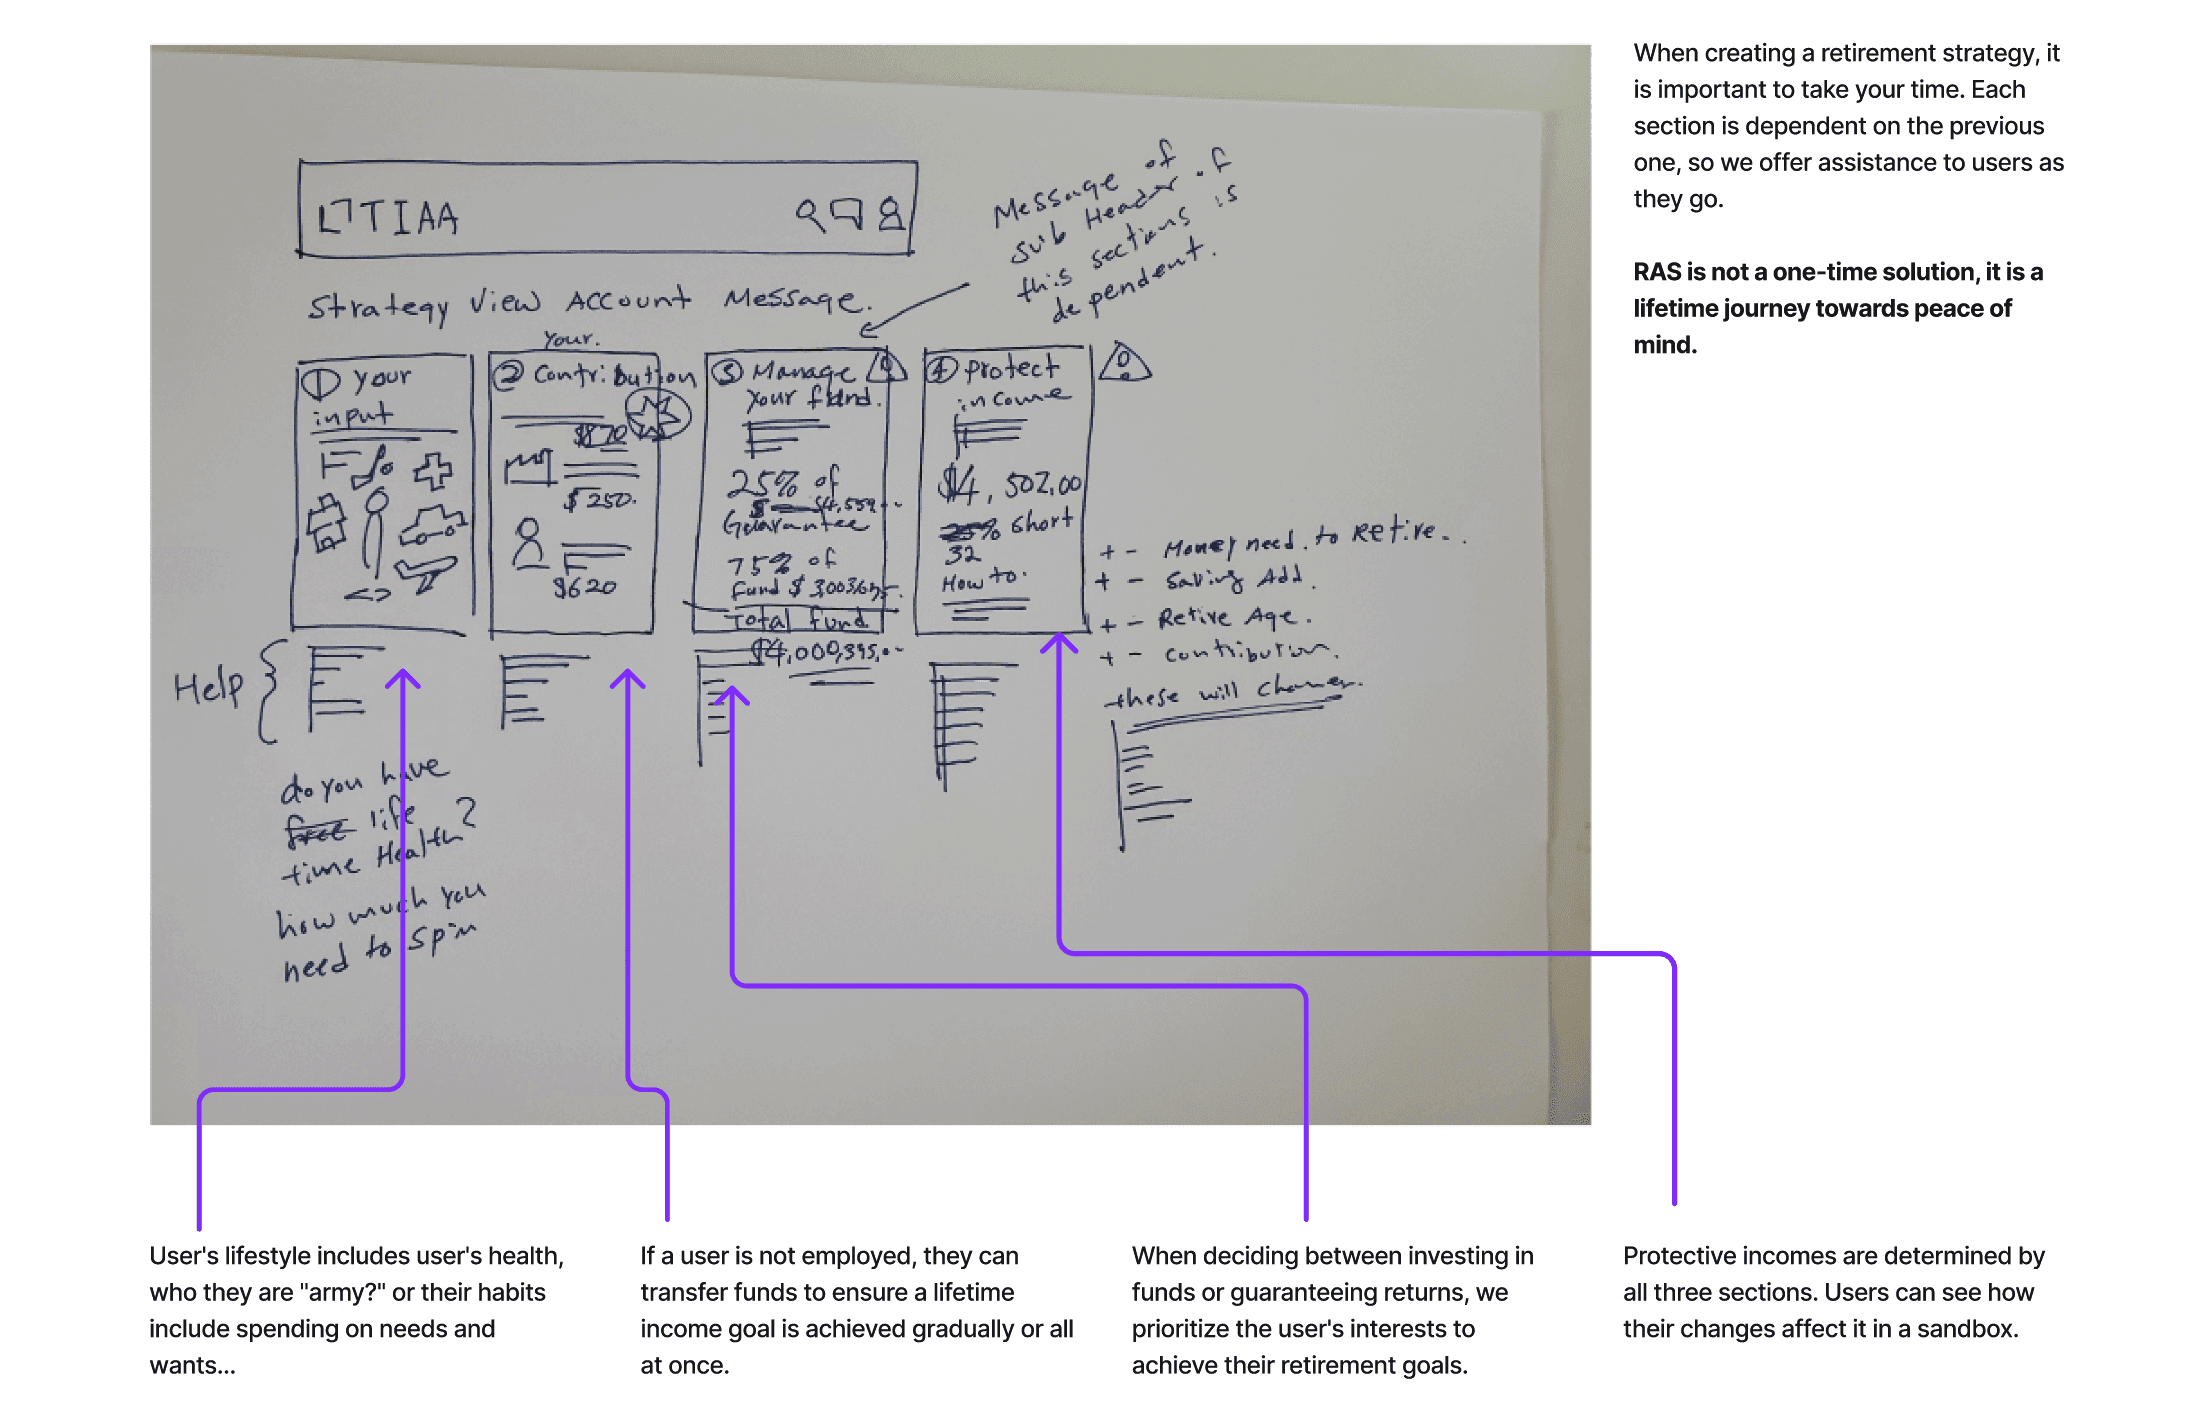
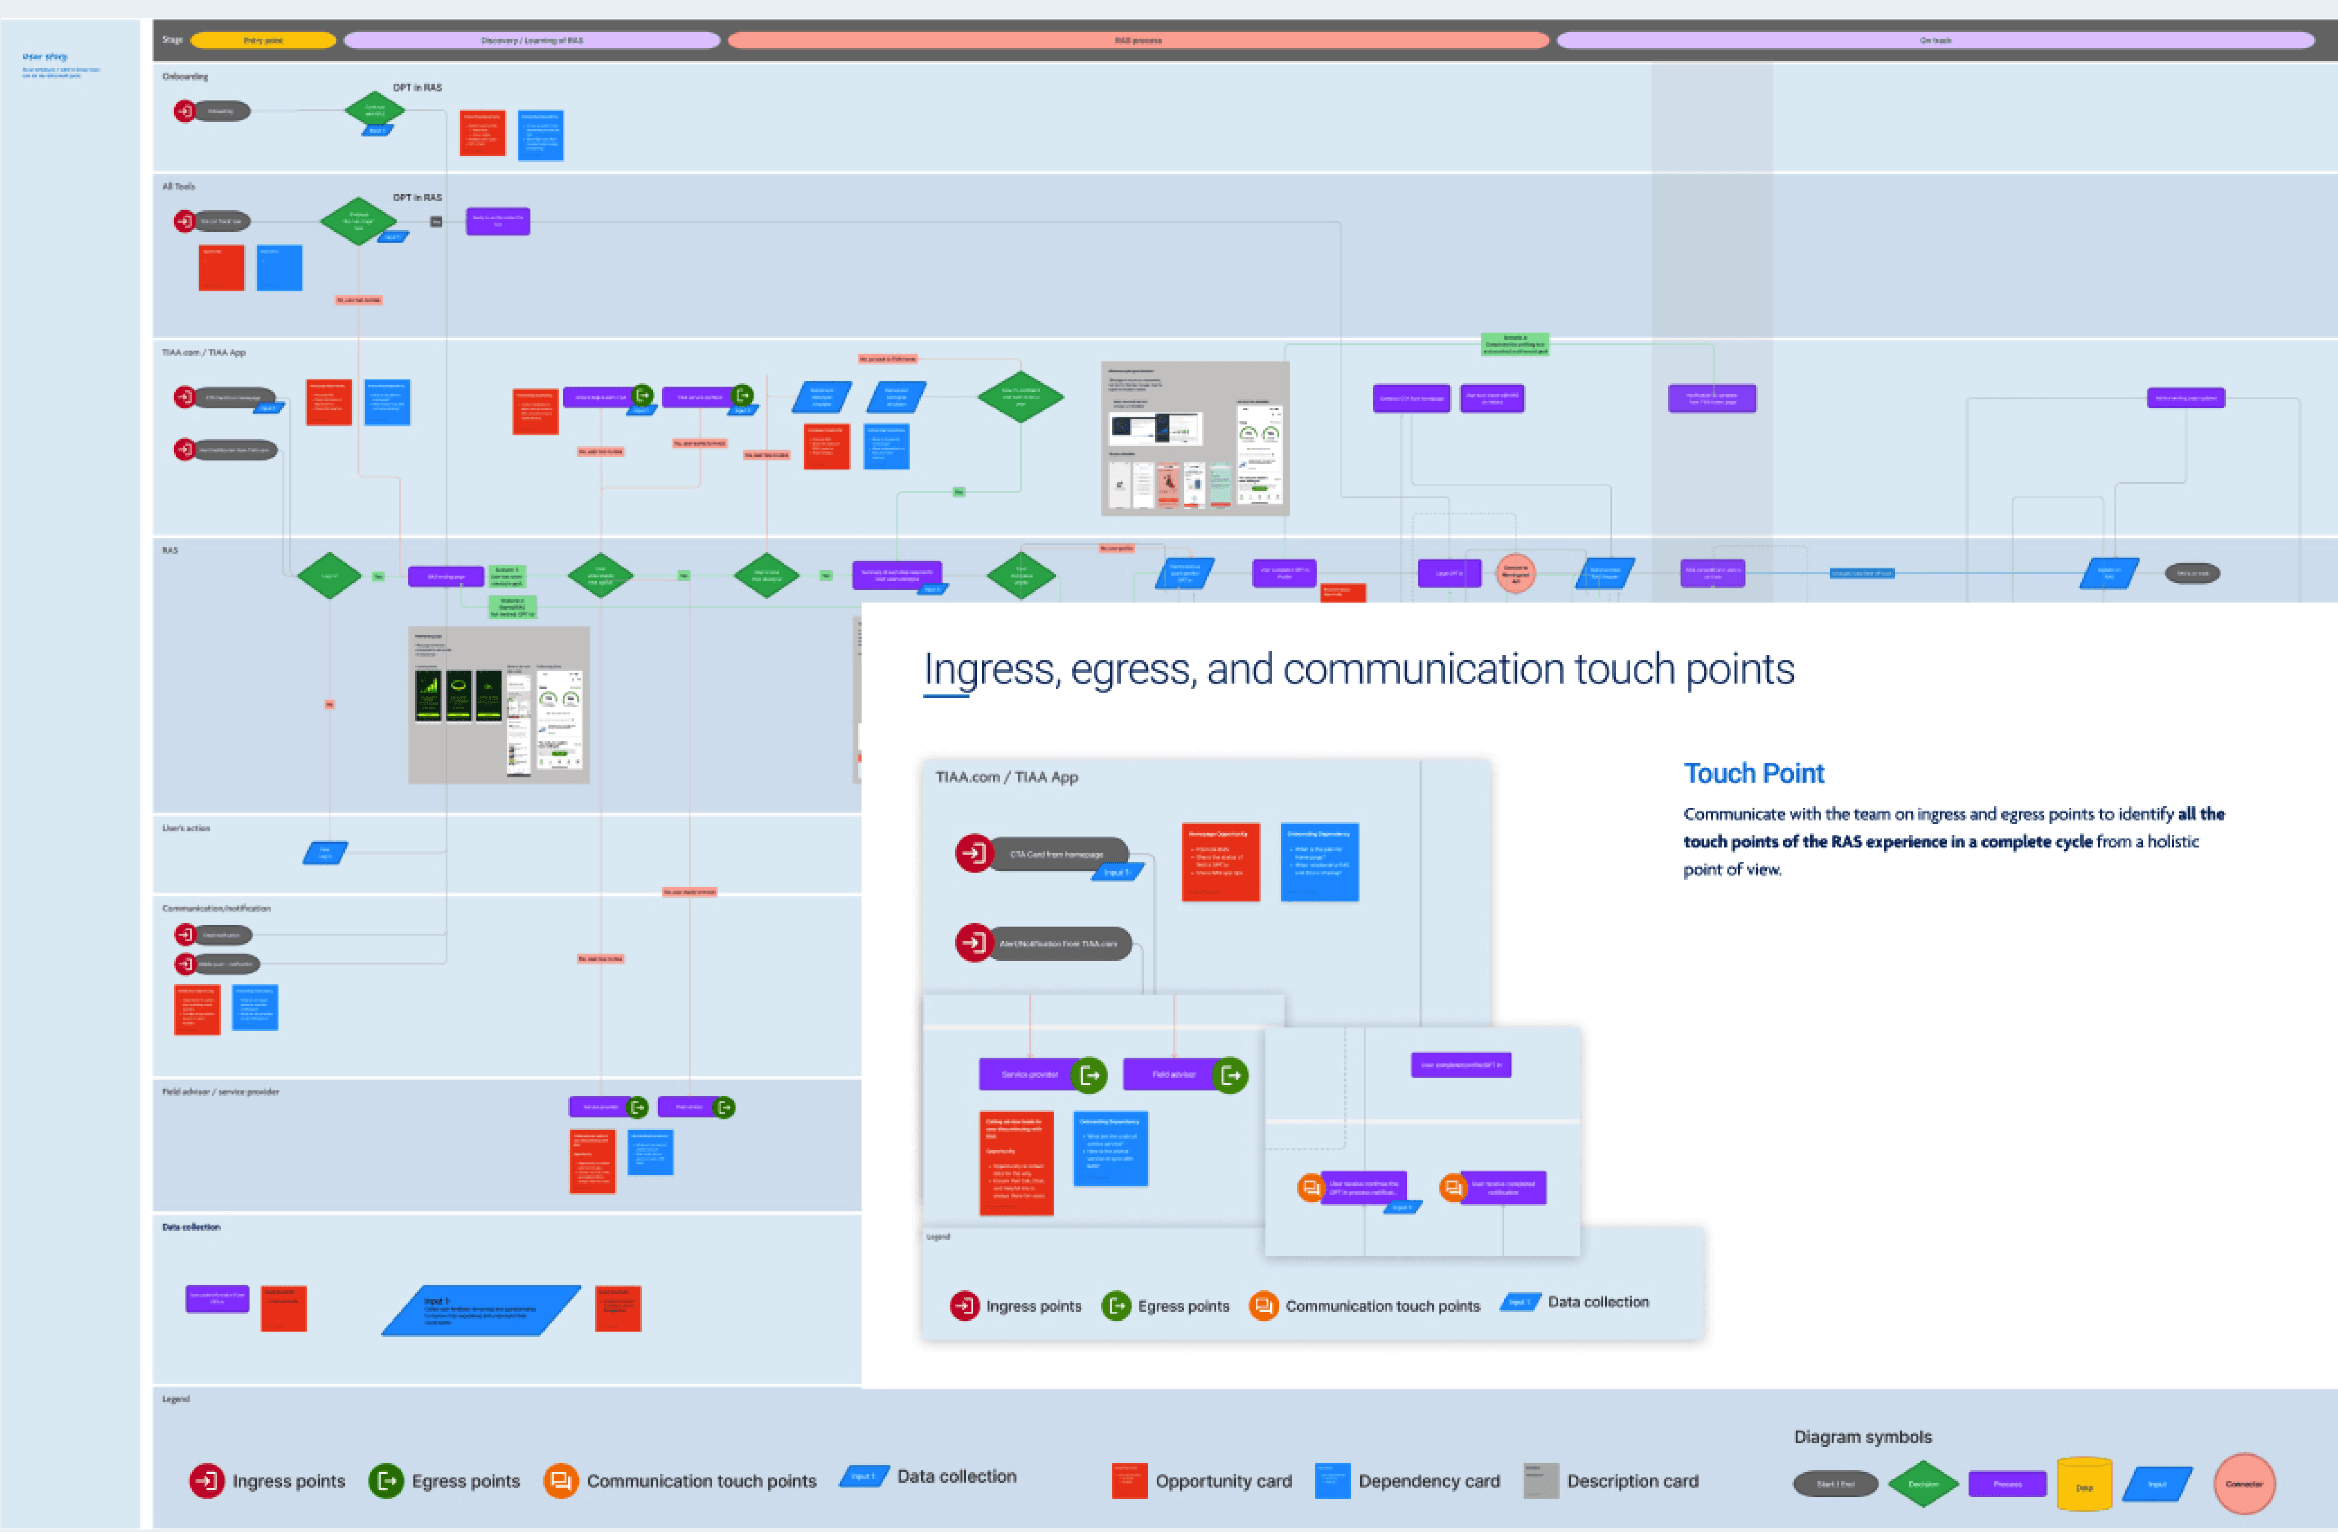
The fix wasn't more screens. It was resequencing the conversation. The old flow asked high-stakes financial questions before establishing any context, which confused people early and forced them to repeat information later. I restructured it to prefill what TIAA already knew from the authenticated profile, and used progressive disclosure so users only saw what was relevant to them in that moment, especially around trade and investment detail. It was an early version of hyper-personalization, adjusting not just content but the shape of the conversation itself based on the user.
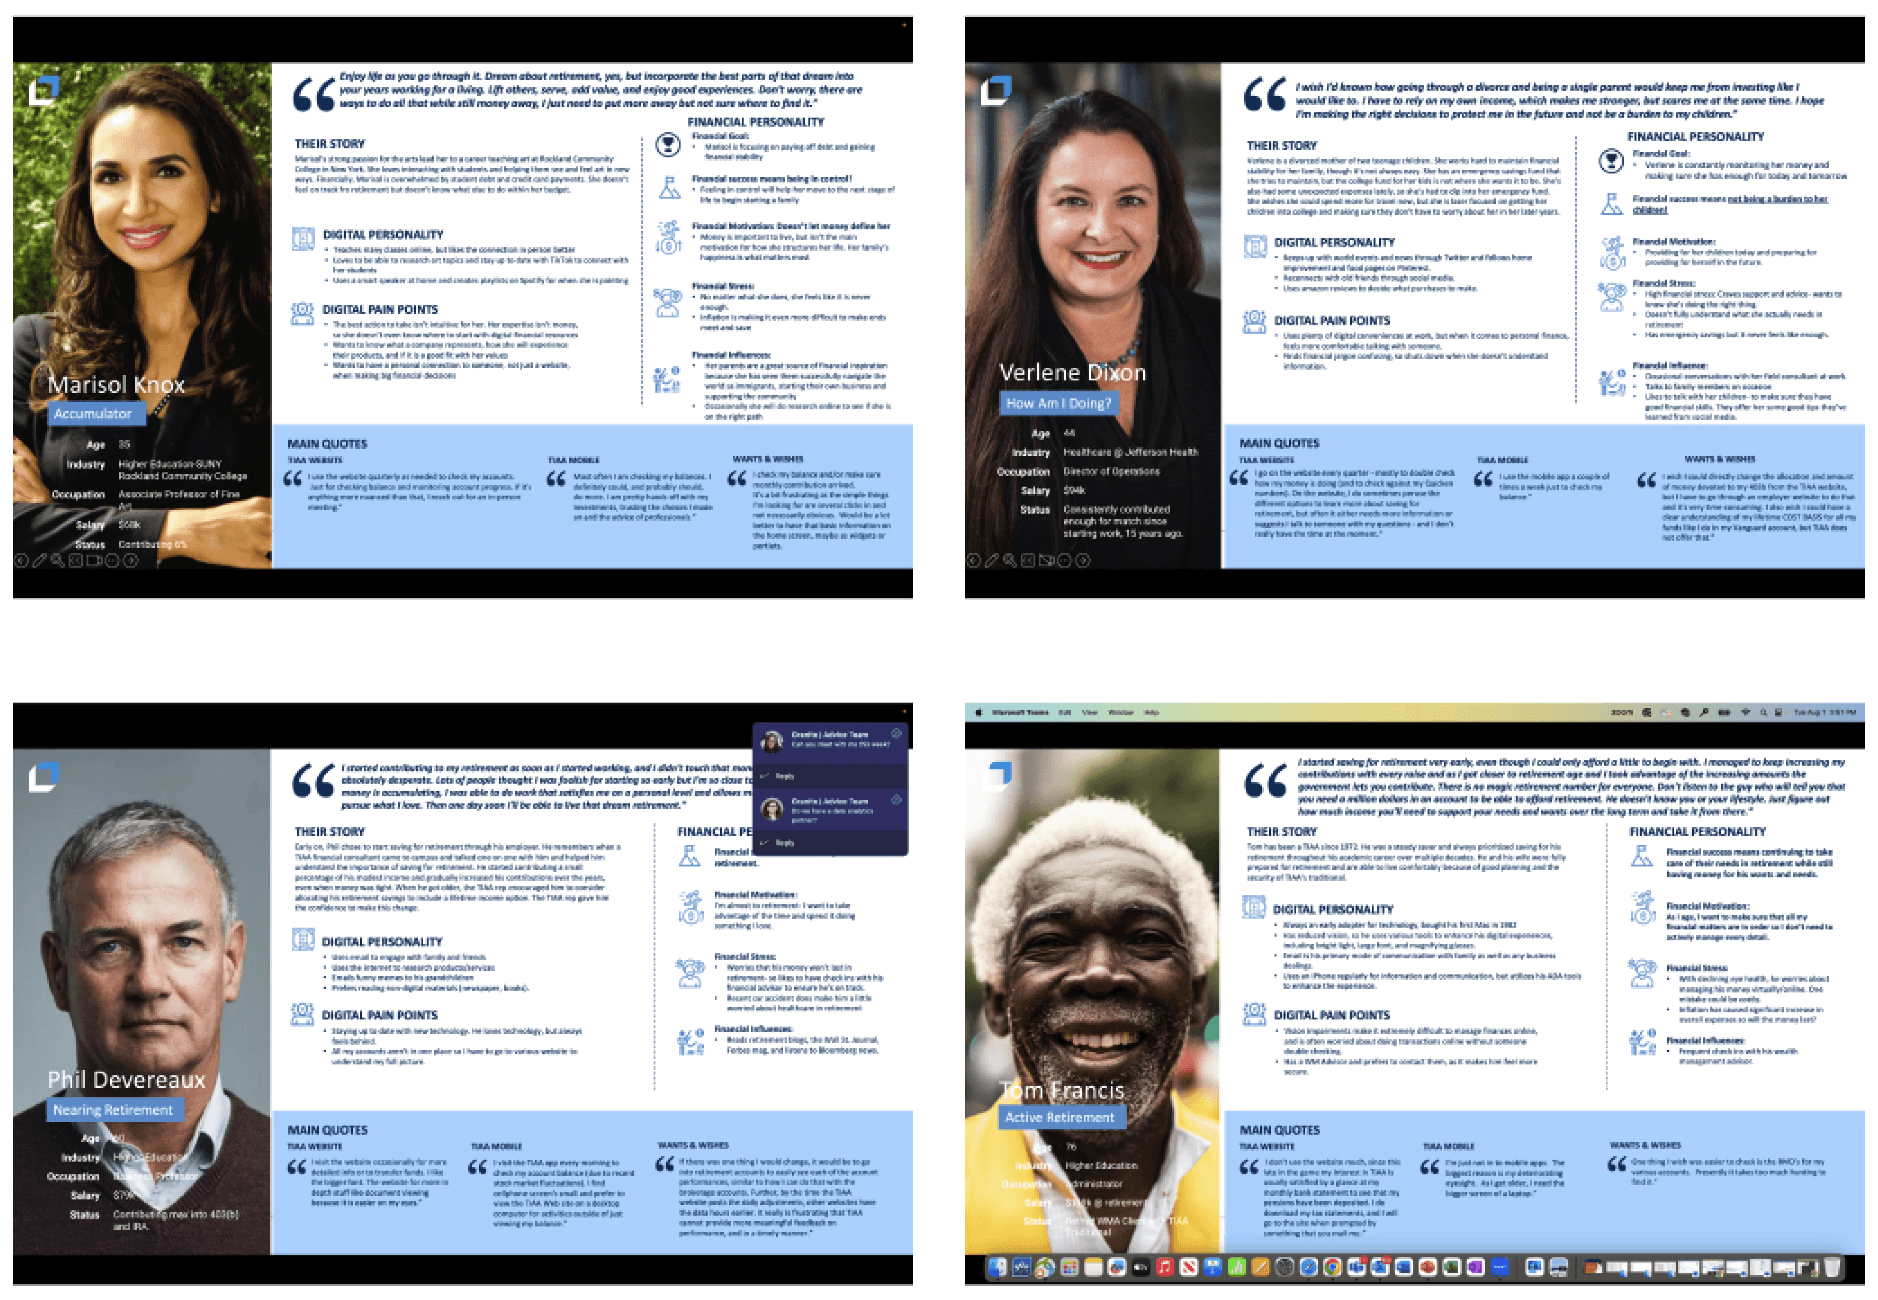
Getting there meant convincing stakeholders this wasn't a screen-edit job. I built the case as a thesis: which user profiles completed the flow, which didn't, and why, tied directly to the minority-retirement-readiness goal. That argument held up once research validated it.
What We Built
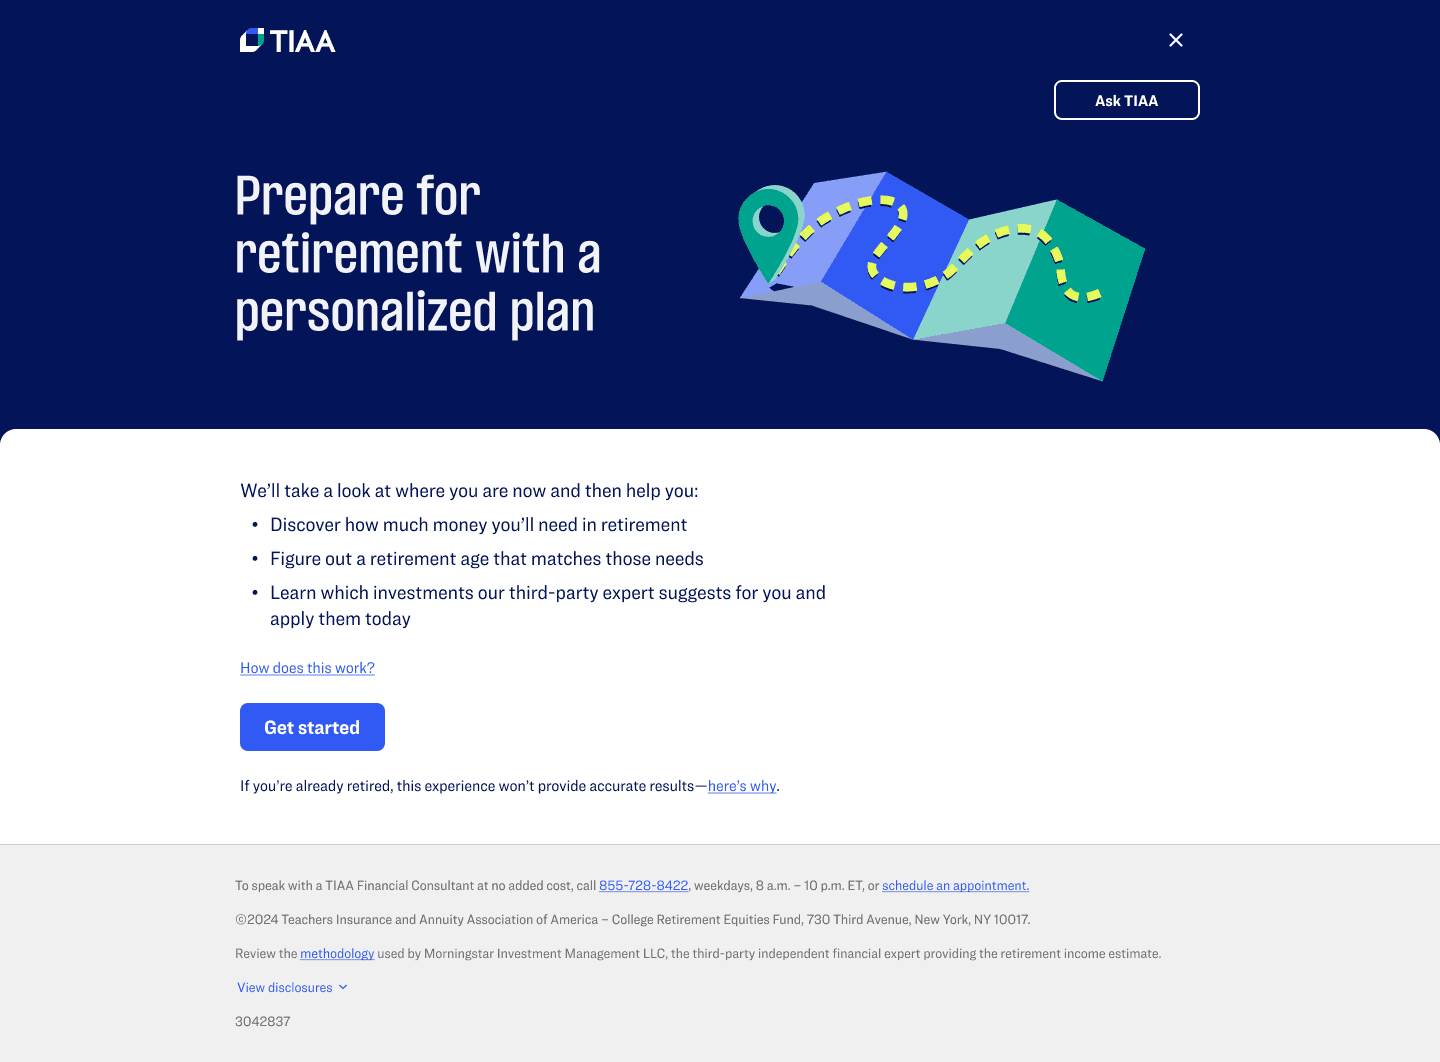
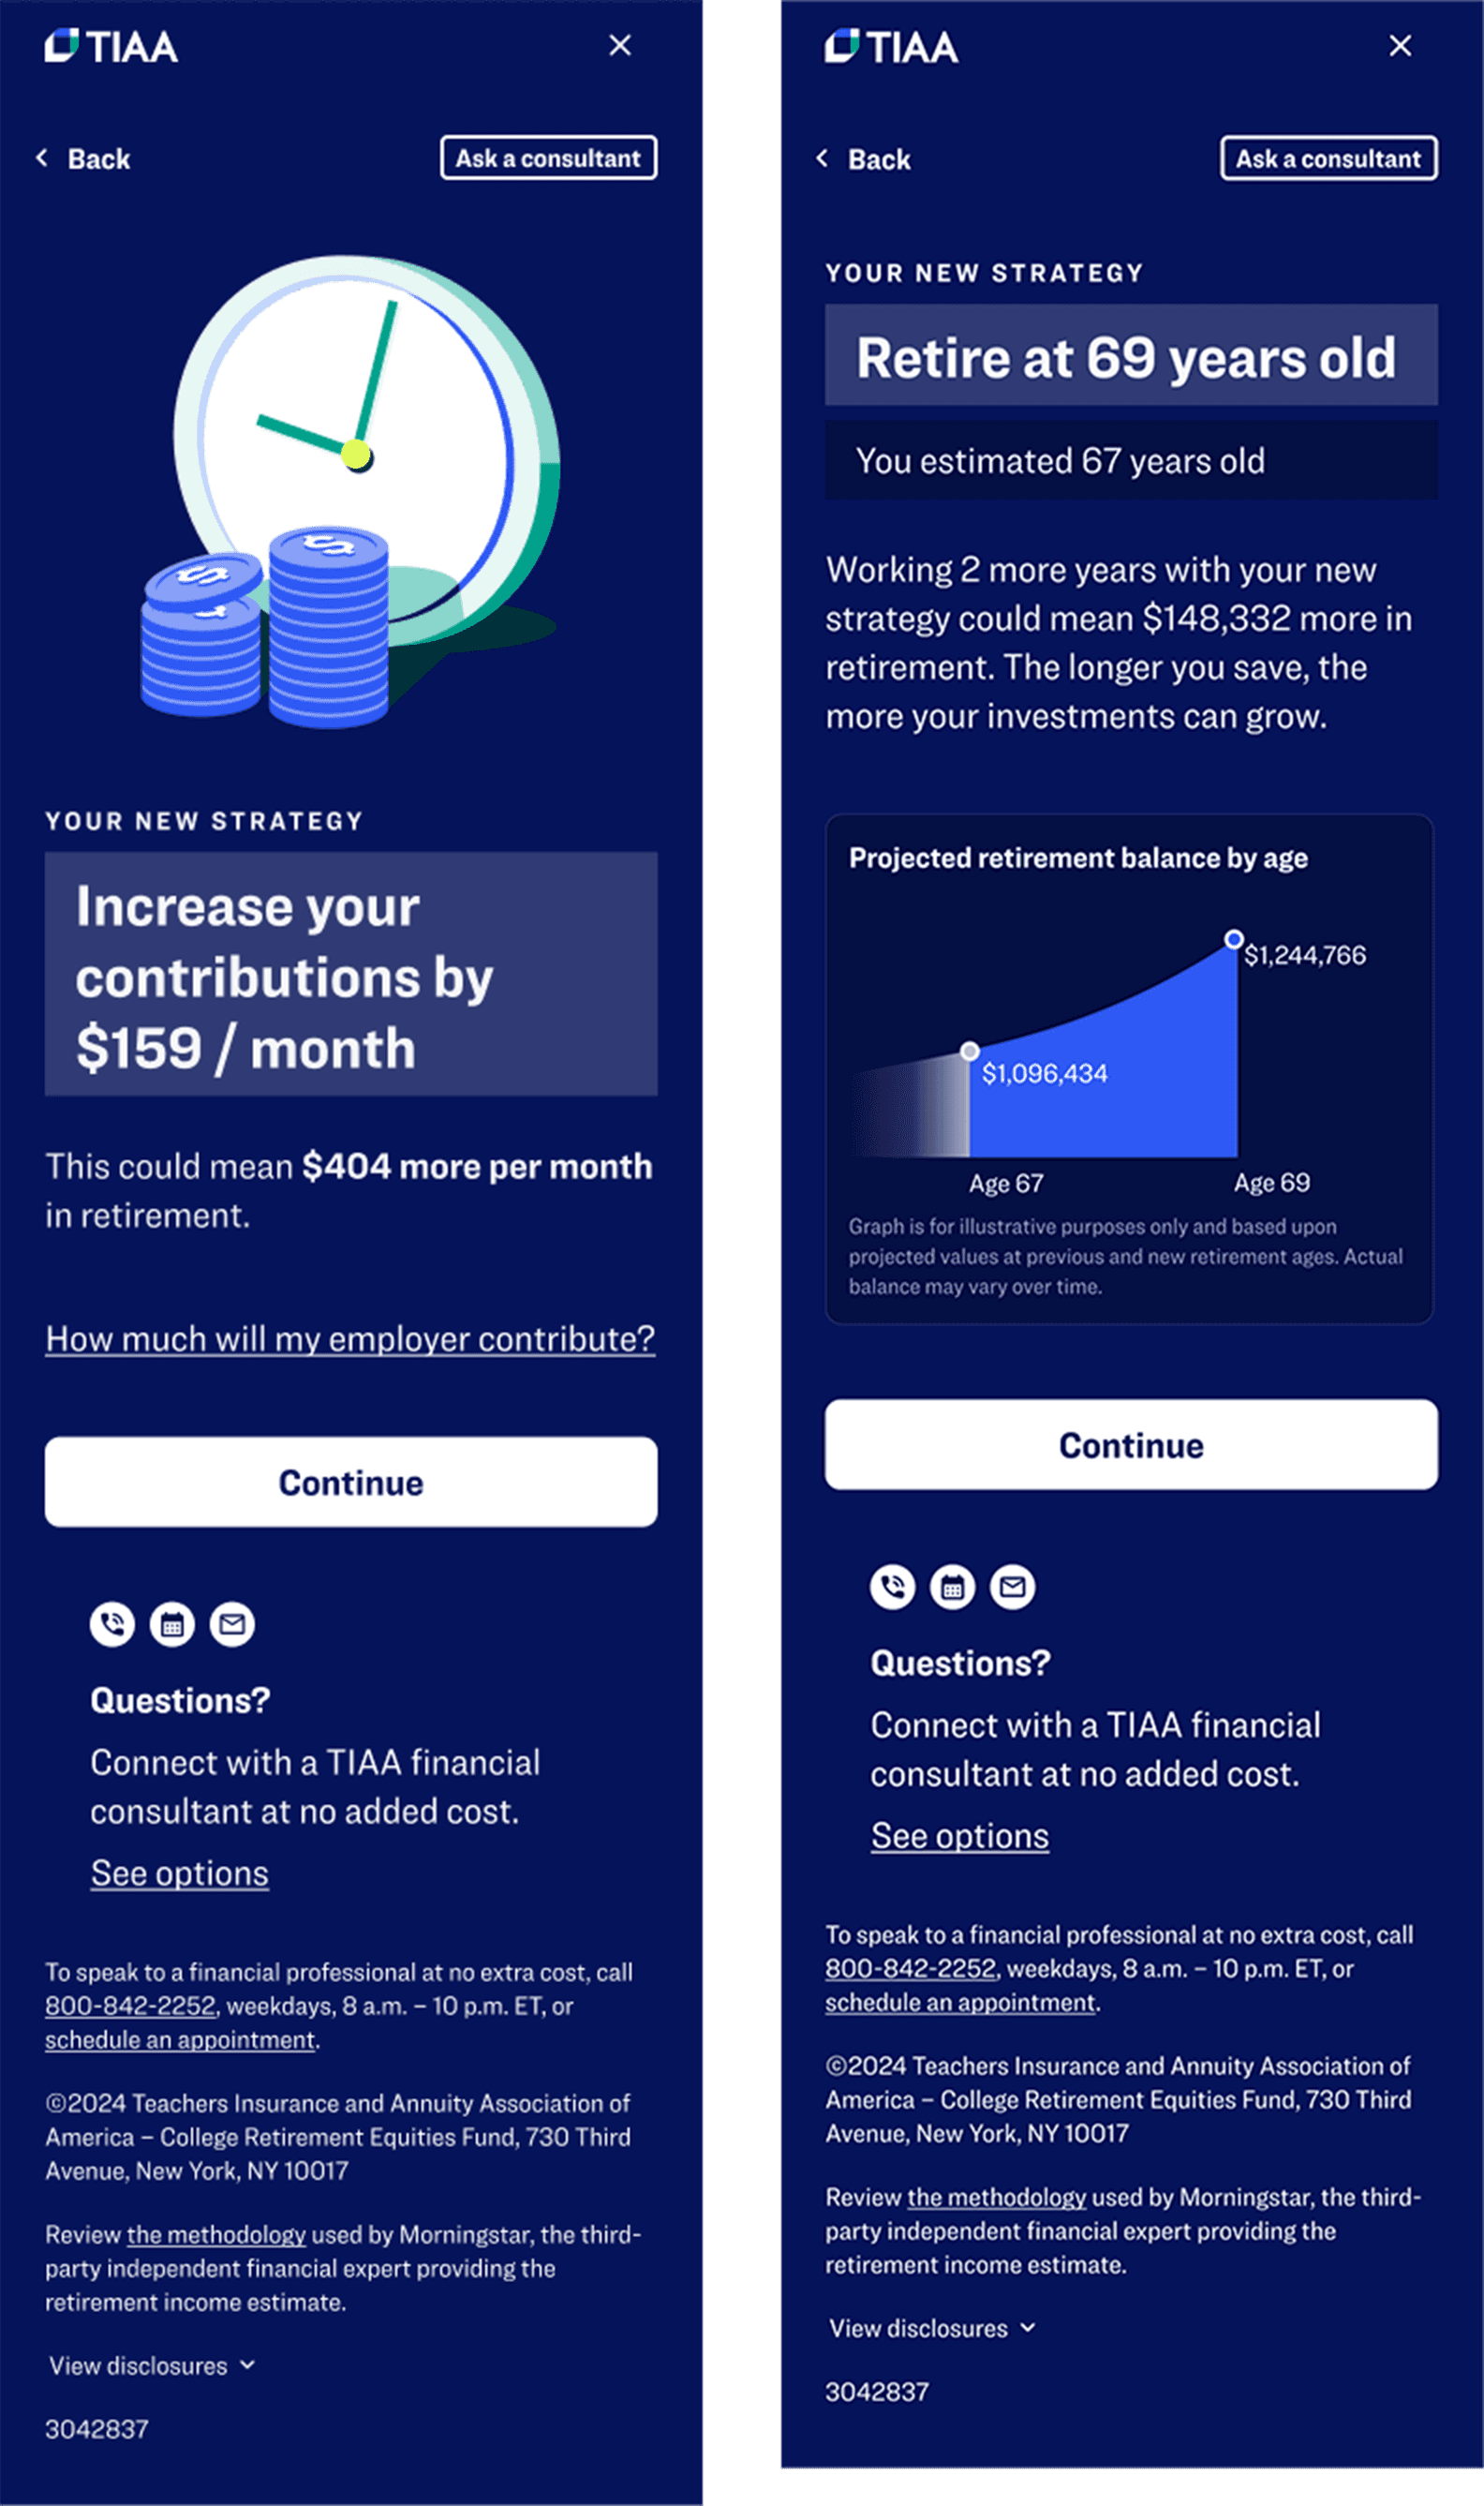
The final system built pages around what TIAA already knew about the user. Someone who'd flagged low familiarity with investing in onboarding, and had no other products activated, got a slower on-ramp: plainer language, fewer decisions per screen, more context before any high-stakes question. Someone with an existing brokerage account and prior contributions got straight to the strategy conversation, no re-explaining basics they'd already shown they understood. This was a first step toward hyper-personalization, a proof of concept for how far a conversation could adapt to a single user, and a case for what that could become with AI doing more of the adapting in real time.

I'm proudest of catching the gap that made this possible. Watching early interviews, I noticed some users answered questions about investing and trade-offs with ease, and others visibly didn't have the frame of reference for them at all. I recognized the second group because I'd been there myself earlier in my life. That was the signal: our research pool skewed toward people who already had exposure to these products, and the users we were failing, the ones tied to our minority-retirement-readiness goal, weren't fully represented in what we were hearing. It took real convincing to get the team to treat that as a design problem and not just a research footnote. It held once we widened who we talked to and heard the same pattern repeat.

With guided AI assistant for customer help
We built inside TIAA's existing design system. It didn't constrain much. What we shipped, specifically the UI that handed off an online conversation to a live account executive without losing context, worked well enough that it got contributed back and adopted into other authenticated flows.
Outcome
NPS 52 → 87
Drop-off rate 85% → 28%
Live support introduced as a net-new feature, giving account executives capacity to help more users without a wait queue
Call quality shifted from executives manually re-entering form data over the phone to users asking specific, trade-level questions, shorter calls, faster closes
The redesign didn't just get more people through the flow. It changed what happened when they didn't finish. Consolidated information made it clear where to pick back up, so partial completions turned into returns instead of drop-offs. And the calls that still happened got better: less form-filling, more actual advising.
RAS shipped and has been live in production since. I confirmed it a year later during a separate contract with TIAA, still getting positive reception internally. It also became the internal reference point for hyper-personalization at TIAA, proof that adapting the conversation itself, not just the UI, moved the numbers.
Reflection
Empathy usually gets treated as too soft to measure. This project proved otherwise, the thing that moved the numbers wasn't a visual overhaul, it was rebuilding the conversation so people felt understood before we asked them anything hard. One piece of feedback from research stuck with me: users said they felt heard and understood, more than in most other financial experiences they'd had.
TIAA
About This Project
TIAA manages retirement plans for members across thousands of institutions. RAS, the Retirement Accumulation System, was the digital front door into that relationship, the flow meant to turn a new participant into someone actively managing their own retirement. Instead, most people who started it never finished. The ones who got stuck called support instead, and every call started from nothing.
The Challenge
TIAA's Retirement Accumulation System was buried two clicks deep under a "Goals" tab, and the flow itself was broken. Only 8 of 100 users who started it finished. 85%+ dropped off before completing a task that was supposed to be the front door into TIAA's retirement products.
The system was supposed to convert people into TIAA's retirement products. Instead it converted them into phone calls. Users got confused, gave up, or called support, and every call started from zero, no context carried over, no sense of where the person had stopped.
The stakes made this harder than a normal onboarding flow. People were mapping out their financial future, and most didn't find out until the end whether they were on track or off track for retirement. Keeping someone engaged through that reveal, instead of losing them to confusion or panic, was as much a design problem as the drop-off numbers.
How I Approached It
I ran a heuristic evaluation on the existing flow first and built a hypothesis from it. Then I tested that hypothesis against real users, hundreds of interviews. The research confirmed most of it, but exposed a gap: financial literacy wasn't just a knowledge problem, it was a background problem. Someone raised around investing had a completely different relationship with financial products than someone with no exposure to them at all. The flow was talking to everyone the same way.
The fix wasn't more screens. It was resequencing the conversation. The old flow asked high-stakes financial questions before establishing any context, which confused people early and forced them to repeat information later. I restructured it to prefill what TIAA already knew from the authenticated profile, and used progressive disclosure so users only saw what was relevant to them in that moment, especially around trade and investment detail. It was an early version of hyper-personalization, adjusting not just content but the shape of the conversation itself based on the user.
Getting there meant convincing stakeholders this wasn't a screen-edit job. I built the case as a thesis: which user profiles completed the flow, which didn't, and why, tied directly to the minority-retirement-readiness goal. That argument held up once research validated it.
What We Built
The final system built pages around what TIAA already knew about the user. Someone who'd flagged low familiarity with investing in onboarding, and had no other products activated, got a slower on-ramp: plainer language, fewer decisions per screen, more context before any high-stakes question. Someone with an existing brokerage account and prior contributions got straight to the strategy conversation, no re-explaining basics they'd already shown they understood. This was a first step toward hyper-personalization, a proof of concept for how far a conversation could adapt to a single user, and a case for what that could become with AI doing more of the adapting in real time.
I'm proudest of catching the gap that made this possible. Watching early interviews, I noticed some users answered questions about investing and trade-offs with ease, and others visibly didn't have the frame of reference for them at all. I recognized the second group because I'd been there myself earlier in my life. That was the signal: our research pool skewed toward people who already had exposure to these products, and the users we were failing, the ones tied to our minority-retirement-readiness goal, weren't fully represented in what we were hearing. It took real convincing to get the team to treat that as a design problem and not just a research footnote. It held once we widened who we talked to and heard the same pattern repeat.
With guided AI assistant for customer help
We built inside TIAA's existing design system. It didn't constrain much. What we shipped, specifically the UI that handed off an online conversation to a live account executive without losing context, worked well enough that it got contributed back and adopted into other authenticated flows.
Outcome
NPS 52 → 87
Drop-off rate 85% → 28%
Live support introduced as a net-new feature, giving account executives capacity to help more users without a wait queue
Call quality shifted from executives manually re-entering form data over the phone to users asking specific, trade-level questions, shorter calls, faster closes
The redesign didn't just get more people through the flow. It changed what happened when they didn't finish. Consolidated information made it clear where to pick back up, so partial completions turned into returns instead of drop-offs. And the calls that still happened got better: less form-filling, more actual advising.
RAS shipped and has been live in production since. I confirmed it a year later during a separate contract with TIAA, still getting positive reception internally. It also became the internal reference point for hyper-personalization at TIAA, proof that adapting the conversation itself, not just the UI, moved the numbers.
Reflection
Empathy usually gets treated as too soft to measure. This project proved otherwise, the thing that moved the numbers wasn't a visual overhaul, it was rebuilding the conversation so people felt understood before we asked them anything hard. One piece of feedback from research stuck with me: users said they felt heard and understood, more than in most other financial experiences they'd had.
TIAA
About This Project
TIAA manages retirement plans for members across thousands of institutions. RAS, the Retirement Accumulation System, was the digital front door into that relationship, the flow meant to turn a new participant into someone actively managing their own retirement. Instead, most people who started it never finished. The ones who got stuck called support instead, and every call started from nothing.
The Challenge
TIAA's Retirement Accumulation System was buried two clicks deep under a "Goals" tab, and the flow itself was broken. Only 8 of 100 users who started it finished. 85%+ dropped off before completing a task that was supposed to be the front door into TIAA's retirement products.
The system was supposed to convert people into TIAA's retirement products. Instead it converted them into phone calls. Users got confused, gave up, or called support, and every call started from zero, no context carried over, no sense of where the person had stopped.
The stakes made this harder than a normal onboarding flow. People were mapping out their financial future, and most didn't find out until the end whether they were on track or off track for retirement. Keeping someone engaged through that reveal, instead of losing them to confusion or panic, was as much a design problem as the drop-off numbers.
How I Approached It
I ran a heuristic evaluation on the existing flow first and built a hypothesis from it. Then I tested that hypothesis against real users, hundreds of interviews. The research confirmed most of it, but exposed a gap: financial literacy wasn't just a knowledge problem, it was a background problem. Someone raised around investing had a completely different relationship with financial products than someone with no exposure to them at all. The flow was talking to everyone the same way.
The fix wasn't more screens. It was resequencing the conversation. The old flow asked high-stakes financial questions before establishing any context, which confused people early and forced them to repeat information later. I restructured it to prefill what TIAA already knew from the authenticated profile, and used progressive disclosure so users only saw what was relevant to them in that moment, especially around trade and investment detail. It was an early version of hyper-personalization, adjusting not just content but the shape of the conversation itself based on the user.
Getting there meant convincing stakeholders this wasn't a screen-edit job. I built the case as a thesis: which user profiles completed the flow, which didn't, and why, tied directly to the minority-retirement-readiness goal. That argument held up once research validated it.
What We Built
The final system built pages around what TIAA already knew about the user. Someone who'd flagged low familiarity with investing in onboarding, and had no other products activated, got a slower on-ramp: plainer language, fewer decisions per screen, more context before any high-stakes question. Someone with an existing brokerage account and prior contributions got straight to the strategy conversation, no re-explaining basics they'd already shown they understood. This was a first step toward hyper-personalization, a proof of concept for how far a conversation could adapt to a single user, and a case for what that could become with AI doing more of the adapting in real time.
I'm proudest of catching the gap that made this possible. Watching early interviews, I noticed some users answered questions about investing and trade-offs with ease, and others visibly didn't have the frame of reference for them at all. I recognized the second group because I'd been there myself earlier in my life. That was the signal: our research pool skewed toward people who already had exposure to these products, and the users we were failing, the ones tied to our minority-retirement-readiness goal, weren't fully represented in what we were hearing. It took real convincing to get the team to treat that as a design problem and not just a research footnote. It held once we widened who we talked to and heard the same pattern repeat.
With guided AI assistant for customer help
We built inside TIAA's existing design system. It didn't constrain much. What we shipped, specifically the UI that handed off an online conversation to a live account executive without losing context, worked well enough that it got contributed back and adopted into other authenticated flows.
Outcome
NPS 52 → 87
Drop-off rate 85% → 28%
Live support introduced as a net-new feature, giving account executives capacity to help more users without a wait queue
Call quality shifted from executives manually re-entering form data over the phone to users asking specific, trade-level questions, shorter calls, faster closes
The redesign didn't just get more people through the flow. It changed what happened when they didn't finish. Consolidated information made it clear where to pick back up, so partial completions turned into returns instead of drop-offs. And the calls that still happened got better: less form-filling, more actual advising.
RAS shipped and has been live in production since. I confirmed it a year later during a separate contract with TIAA, still getting positive reception internally. It also became the internal reference point for hyper-personalization at TIAA, proof that adapting the conversation itself, not just the UI, moved the numbers.
Reflection
Empathy usually gets treated as too soft to measure. This project proved otherwise, the thing that moved the numbers wasn't a visual overhaul, it was rebuilding the conversation so people felt understood before we asked them anything hard. One piece of feedback from research stuck with me: users said they felt heard and understood, more than in most other financial experiences they'd had.
TIAA
About This Project
TIAA manages retirement plans for members across thousands of institutions. RAS, the Retirement Accumulation System, was the digital front door into that relationship, the flow meant to turn a new participant into someone actively managing their own retirement. Instead, most people who started it never finished. The ones who got stuck called support instead, and every call started from nothing.
The Challenge
TIAA's Retirement Accumulation System was buried two clicks deep under a "Goals" tab, and the flow itself was broken. Only 8 of 100 users who started it finished. 85%+ dropped off before completing a task that was supposed to be the front door into TIAA's retirement products.
The system was supposed to convert people into TIAA's retirement products. Instead it converted them into phone calls. Users got confused, gave up, or called support, and every call started from zero, no context carried over, no sense of where the person had stopped.
The stakes made this harder than a normal onboarding flow. People were mapping out their financial future, and most didn't find out until the end whether they were on track or off track for retirement. Keeping someone engaged through that reveal, instead of losing them to confusion or panic, was as much a design problem as the drop-off numbers.
How I Approached It
I ran a heuristic evaluation on the existing flow first and built a hypothesis from it. Then I tested that hypothesis against real users, hundreds of interviews. The research confirmed most of it, but exposed a gap: financial literacy wasn't just a knowledge problem, it was a background problem. Someone raised around investing had a completely different relationship with financial products than someone with no exposure to them at all. The flow was talking to everyone the same way.
The fix wasn't more screens. It was resequencing the conversation. The old flow asked high-stakes financial questions before establishing any context, which confused people early and forced them to repeat information later. I restructured it to prefill what TIAA already knew from the authenticated profile, and used progressive disclosure so users only saw what was relevant to them in that moment, especially around trade and investment detail. It was an early version of hyper-personalization, adjusting not just content but the shape of the conversation itself based on the user.
Getting there meant convincing stakeholders this wasn't a screen-edit job. I built the case as a thesis: which user profiles completed the flow, which didn't, and why, tied directly to the minority-retirement-readiness goal. That argument held up once research validated it.
What We Built
The final system built pages around what TIAA already knew about the user. Someone who'd flagged low familiarity with investing in onboarding, and had no other products activated, got a slower on-ramp: plainer language, fewer decisions per screen, more context before any high-stakes question. Someone with an existing brokerage account and prior contributions got straight to the strategy conversation, no re-explaining basics they'd already shown they understood. This was a first step toward hyper-personalization, a proof of concept for how far a conversation could adapt to a single user, and a case for what that could become with AI doing more of the adapting in real time.
I'm proudest of catching the gap that made this possible. Watching early interviews, I noticed some users answered questions about investing and trade-offs with ease, and others visibly didn't have the frame of reference for them at all. I recognized the second group because I'd been there myself earlier in my life. That was the signal: our research pool skewed toward people who already had exposure to these products, and the users we were failing, the ones tied to our minority-retirement-readiness goal, weren't fully represented in what we were hearing. It took real convincing to get the team to treat that as a design problem and not just a research footnote. It held once we widened who we talked to and heard the same pattern repeat.
With guided AI assistant for customer help
We built inside TIAA's existing design system. It didn't constrain much. What we shipped, specifically the UI that handed off an online conversation to a live account executive without losing context, worked well enough that it got contributed back and adopted into other authenticated flows.
Outcome
NPS 52 → 87
Drop-off rate 85% → 28%
Live support introduced as a net-new feature, giving account executives capacity to help more users without a wait queue
Call quality shifted from executives manually re-entering form data over the phone to users asking specific, trade-level questions, shorter calls, faster closes
The redesign didn't just get more people through the flow. It changed what happened when they didn't finish. Consolidated information made it clear where to pick back up, so partial completions turned into returns instead of drop-offs. And the calls that still happened got better: less form-filling, more actual advising.
RAS shipped and has been live in production since. I confirmed it a year later during a separate contract with TIAA, still getting positive reception internally. It also became the internal reference point for hyper-personalization at TIAA, proof that adapting the conversation itself, not just the UI, moved the numbers.
Reflection
Empathy usually gets treated as too soft to measure. This project proved otherwise, the thing that moved the numbers wasn't a visual overhaul, it was rebuilding the conversation so people felt understood before we asked them anything hard. One piece of feedback from research stuck with me: users said they felt heard and understood, more than in most other financial experiences they'd had.